Third Quarter Review & Outlook
November 1, 2026
Though Inflation Persists, Fed Pauses On Rate Hike
No sooner did the Federal Reserve opt to leave interest rates in place last Wednesday, when the next day’s economic data made its decision to pause appear wrong — at least to me!
Its decision to leave rates unchanged since its September hike to a target range of 3.75% to 4.00%, comes amid economic data that is both "healthy" and "unhealthy." (See boxes.)
In the healthy category, the Commerce Department said that third-quarter GDP rose at an annual rate of 3.4%. (The inflation- and seasonally-adjusted figure was above market expectations.) That level of expansion follows first- and second-quarter growth rates of 2.5% and 2.2%, respectively. While the 3.4% rate will almost certainly be revised, it certainly suggests that the U.S. economy is on a sound footing.
Credit both business (AI infrastructure) and consumer spending.
In the first case, business investment has soared to an annual rate of 12.7%. AI-related spending accounts for most of that as evidenced by information processing equipment growing more than 37% last quarter. But AI spending is not the entire story.
Remember President Trump’s One Big Beautiful Bill Act (OBBBA) of 2025? Well, the Congressional Budget Office estimates that it will account for 0.9 percentage points of this year’s real GDP growth. Another provision of OBBBA is that businesses may now deduct capital expenses immediately. That appears to be helping equipment sales and accelerating spending on R&D.
As for consumer spending, the picture is more nuanced — a mix of good and bad news.
While economists forecasted real consumer spending to rise 3.5% in the July to September quarter, it actually rose 3.8%. And, as a reminder of just how important consumers are to the U.S. economy, their spending contributed about 2.5 percentage points of the 3.4% GDP growth rate!
That the consumer (collectively) stepped up to the plate at a time of elevated fuel prices warrants further investigation.
For one thing, energy prices largely stabilized last quarter, with the biggest impact having already occurred in the second quarter. Notably, residential electricity costs jumped 6.9% per kWh from January through July. During that same period, the national average for a gallon of regular gas spiked 40% to $3.93 a gallon. (As of this writing, the national average is $4.31 — a 53% increase.)
How is the despondent consumer managing such a financial drag?
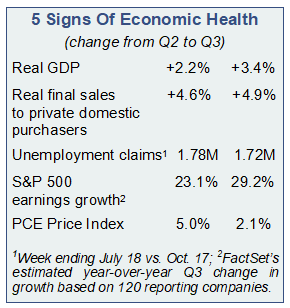
Surprisingly, credit card borrowing has remained steady, as have default rates on most types of borrowing. But, it turns out, higher energy costs are being offset by a combination of cutting back on groceries, less dining out, fine-tuning home thermostats, and more ominously, reducing savings. At the end of the first quarter, Americans’ aggregate savings rate was 4.1%; that fell to 3.8% in September.
Of course, more affluent baby boomers continue to account for a disproportionate amount of consumer spending (though in the aggregate, mortality is chipping away at that every year, and is being redirected towards health care). Regardless, the larger point is that the economy is growing, the unemployment rate is steady and manageable at 4.5%, while first-time unemployment claims remain low. Against that macro snapshot, by a vote of 10 to 2, the Fed’s rate-setting committee was content to hold rates steady.
But what about inflation, which, after all, is one of the Fed’s main responsibilities?
As we all know, rising oil prices have recently been the prime driver behind inflation. But the hope, of course, is that a resolution to the Iran war (started in late February) will eventually pull energy prices lower. (President Trump’s pact with Russia last month to buy their diesel is unlikely to materially help.)
While retreating fuel costs would most certainly ease pricing pressures, the combination of AI infrastructure borrowing, the federal government’s deficit spending, and to lesser a degree tariffs, are each fanning inflation.
So just how bad is that problem?
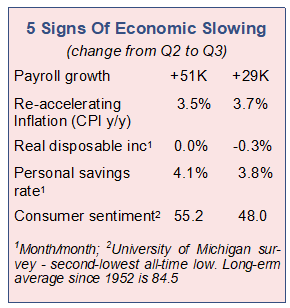
If the Fed’s inaction last week is the appropriate guide, not all that bad. However, since September, inflation has incrementally reaccelerated. So-called headline inflation, CPI, rose 0.6% in September, resulting in a year-over-year increase of 3.7%. Furthermore, September’s core PCE measure (favored by the Fed itself) is back up to 3.1% year-over-year, which is well above the central bank’s long-term inflation target of 2%. Core CPI (which also strips out food and energy) rose 0.3% from August to September, while the Fed itself forecasts its rise of 3.4% this year as unlikely to retreat to its target until 2029.
Against that backdrop, it’s hardly surprising that the University of Michigan’s survey of inflation expectations has jumped significantly, while its sister consumer sentiment survey (whose methodologies recently changed) has fallen to a near- all-time low as years of declining purchasing power (intensified by the Covid lockdowns) are squeezing Americans.
That said, with the Fed clearly focusing at last month’s meeting on the economy’s strengths rather than its weaknesses, and given the strong evidence that there is little risk of recession, Chairman Kevin Warsh and others feel that there’s still time to be more measured in raising rates.
Perhaps. But the Fed has a long history of procrastinating in its inflation fights. In more recent times, it was asleep at the wheel in 2021-’22 and 2004-’06, and far worse in 1965-’79. (Late in ’79, Paul Volcker tightened money supply, slashing inflation from 14.8% in March 1980 to 3% in 1983.)
So why the delay now?
Some charge that with just six days between its October 28 rate-setting meeting and the November 3 midterm elections, an already politically embattled Fed is in no mood for another White House fight — a charge that Mr. Warsh vehemently refutes.
Politically motivated or not, the bond market was correct in forecasting an October pause. But unless inflation shows significant signs of easing by the Fed’s December meeting, it will have no alternative to hiking rates, probably continuing to do so until its own inflation targets are realized. That hasn’t been the case for 5-plus years — since February 2021. While no one will enjoy swallowing their inflation medicine, it may be sorely needed.
— John Bonnanzio